What the provision is in service of.
Finance & Provision
Money is calm when you know what is coming in, what must go out, and what you will not pretend you can afford.
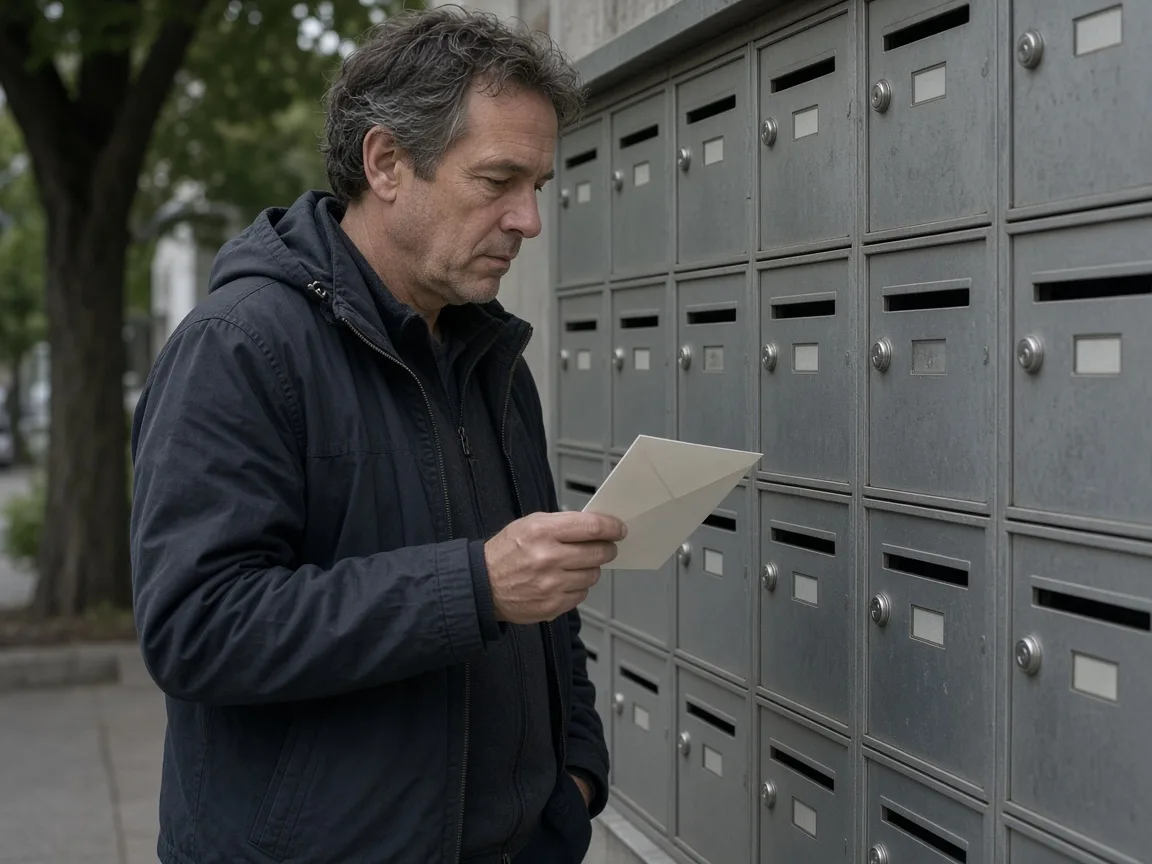
The envelope sits on the bench for three days. You know roughly what it is. You also know that opening it will force a decision, so you work around it. That is not a character flaw unique to you. It is what men do when money has become a mood instead of a list.
Finance and provision are not a luxury watch or a loud opinion about markets. They are the ability to meet your obligations without panic, and to make the next money decision with the numbers in front of you. A man who can do that is easier to live with. He does not have to hide the account.
Nothing on this page is personal financial advice. Your tax, your debts, and your household are yours. What follows is a way to look at them without theatre.
Why the numbers change how you treat people
Money stress leaks. It shortens your patience. It makes you say yes to work you resent, or no to a cost that was actually fine, because you do not know which is which. When you do not know the month, every purchase feels like a risk and every conversation about money feels like an attack.
Looking after the household purse is part of being reliable. If someone shares a life with you, they should not have to guess whether the bills are handled. If you live alone, you still owe yourself a clear picture. Shame about money usually produces avoidance, and avoidance produces a worse month.
You can influence a weekly look at the cash. You cannot control a redundancy, a rate rise, or a repair you did not schedule. Wisdom is separating those. Courage is opening the account anyway. Temperance is not spending to soothe a feeling you have not named. Justice is not hiding a debt from a person who will share the consequence.
A calm money life is not the same as a wealthy one. Plenty of high incomes are chaotic. Plenty of ordinary incomes are orderly. Order is the part you can practice this week.
See the month before you judge it
Once a week, twenty minutes is enough if you actually do it. Write what came in. Write what must go out before you get to choose: rent or mortgage, food, power, transport, the minimum on any debt, anything you have already promised a person. What is left is the money you may decide about. If nothing is left, that is the fact. Do not decorate it.
Use the same few categories every week so you can compare. Housing. Food. Transport. Debts. Everything else. You are not building a spreadsheet career. You are stopping the month from being a surprise.
If you share money with a partner, do this where they can see the categories, even if one of you does the typing. Secret competence is not the same as shared trust. If the conversation gets hot, stick to the list. The list is less insulting than a speech about who is careful.
Irregular costs are where orderly men still get ambushed. Rego, insurance, a school camp, a dental visit, Christmas. A small amount set aside each week for those, in an account you do not treat as spending money, will do more for your nerves than a clever investment idea you do not understand.
Make the next decision slowly enough
Before a non-essential spend, ask two questions. Does this fit what is left after the obligations? Will I still agree with it on Friday? If you cannot answer, wait a day. Waiting a day is not weakness. It is how you stop a mood from signing the card.
Debt is a tool with a price. If you carry it, know the interest and the minimum, and know which debt you are reducing on purpose. Paying a little extra on the expensive one, while you keep the minimums on the rest, is a plain method. It is not a promise that you will be clear in a month. It is a direction.
Do not take a product, a course, or a tip from a stranger because it sounds like manhood. If you do not understand how you get your money back, you do not understand the decision. Boring accounts, boring bills, and a boring buffer will outperform a story you repeat at a barbecue.
If the numbers are bad, tell one competent person. A partner, a mate who is steady with money, or a qualified adviser if the mess is larger than a weekly review. Hiding it protects your pride for a short time and makes the repair harder. This page will not pretend a notebook fixes a legal or tax problem. It will get you to the point where you know what to take to that conversation.
A money habit you can keep when you are tired
Put the weekly twenty minutes on the same day. Sunday night or Monday morning. Same chair. Phone in another room for that slice. If you miss it, do ten minutes the next day. Do not wait for a free weekend that will not arrive.
Automate what you can trust. Rent. The minimums. A small transfer to the irregular-cost account the day you are paid. Automation is not laziness. It is a way of keeping a promise when you are busy. Check it once a month so a changed bill does not silently break it.
Give yourself a small amount you do not have to justify, if the obligations are met. Men who ban every pleasure tend to break the ban loudly. A known amount for a beer, a book, or a lunch is easier to live with than a rule you resent.
The aim is a household, or a single life, that is not run by dread. You will still have tight months. You will know they are tight because you looked, not because the envelope stayed on the bench.
One month of looking, without a new personality
He picks Sunday evening. The first week he only writes the obligations and what hit the account. He is surprised by a subscription he forgot and by how much food cost when the week was chaotic. He does not build a new budget religion that night. He cancels the subscription he does not use, and he writes a rough number for groceries that matches what actually happened, not what he wishes.
Week two he moves a small transfer, the day he is paid, into an account named for irregular costs. It is not a large amount. It is the rego and the insurance broken into weeks so they stop being emergencies. He tells his partner the categories if he shares a life, including the part that is tighter than he had implied. The conversation is awkward for ten minutes and calmer for the rest of the month, because the numbers are no longer a secret mood.
Week three a mate suggests a purchase that sounds like a shortcut. He waits a day, checks what is left after obligations, and says no. The no is not a moral performance. The money was already spoken for by the power bill and the extra on the expensive debt. He keeps the minimums and adds a little to the one debt he chose. He does not open a new product he does not understand.
Week four the car needs a repair he did not plan. It hurts. It does not surprise him into hiding, because the weekly page already has a line for irregular costs and he can see the gap. He adjusts the 'everything else' number for two weeks instead of pretending the month is fine. He still does the Sunday twenty minutes. Skipping the look because the news is bad is how the envelope goes back on the bench.
At the end of the month he has not become wealthy. He knows the shape of the month, he has one automated transfer, and he has stopped one leak. That is financial power at the scale a tired man can practice. If your numbers are heavier than this sketch, the same first step applies: obligations on paper, one weekly appointment with them, and a qualified person if the mess is beyond a household list.
Keep the page where you will actually open it. A note on the fridge beats a perfect system you avoid. If you share money, agree the ten minutes are about the list, not about character. You can be annoyed and still read the number. You can be the higher earner and still owe a clear picture. Power, in this domain, is the absence of nasty surprises you could have seen coming. It will not make you impressive. It will make the next hard bill a decision instead of a ambush.
If you are paid irregularly, do the same look on the day money arrives and again mid-cycle, not only on Sunday. Contractors and shift workers get hurt by pretending every week looks like a salary week. Put the lean week on the page while it is still ahead of you. Then the full week does not feel like permission to spend the buffer you needed. That single habit, repeated, is worth more than a new app full of categories you will not open.
Put it into practice
Five minutes. One piece of paper. You are sketching this week, not your whole financial life.
- Write what must be paid before you get a choice. Only the obligations, in a short list.
- Write one number you think is left after those, and one bill or cost that usually surprises you.
- Put a twenty-minute money look on a specific day this week. Write the day next to the list.
Take it further with Iron Compass
A weekly money check you can repeat, with the same categories and a note about what surprised you, is a habit you can keep in the Iron Compass app. Open it at ironcompassai.com/app. This page is not financial advice.
The journal has a twenty-minute weekly money check you can use as soon as you finish the list above, along with pieces on cash buffers and a plain resilience routine. Do the five minutes first so the article has something to attach to. None of it replaces advice from someone qualified about your own situation.
Keep going
A neighbouring domain, and pieces from the journal you can read today.
Curated cashflow, buffer, and money discipline guides.
Weekly cash flow clarity, buffer protection, and low-risk decisions.
An eight-week sprint to tighten burn, add revenue, and automate the basics.
Use AI to speed reviews without losing judgment on the numbers.